Roth Catch-Up Contributions
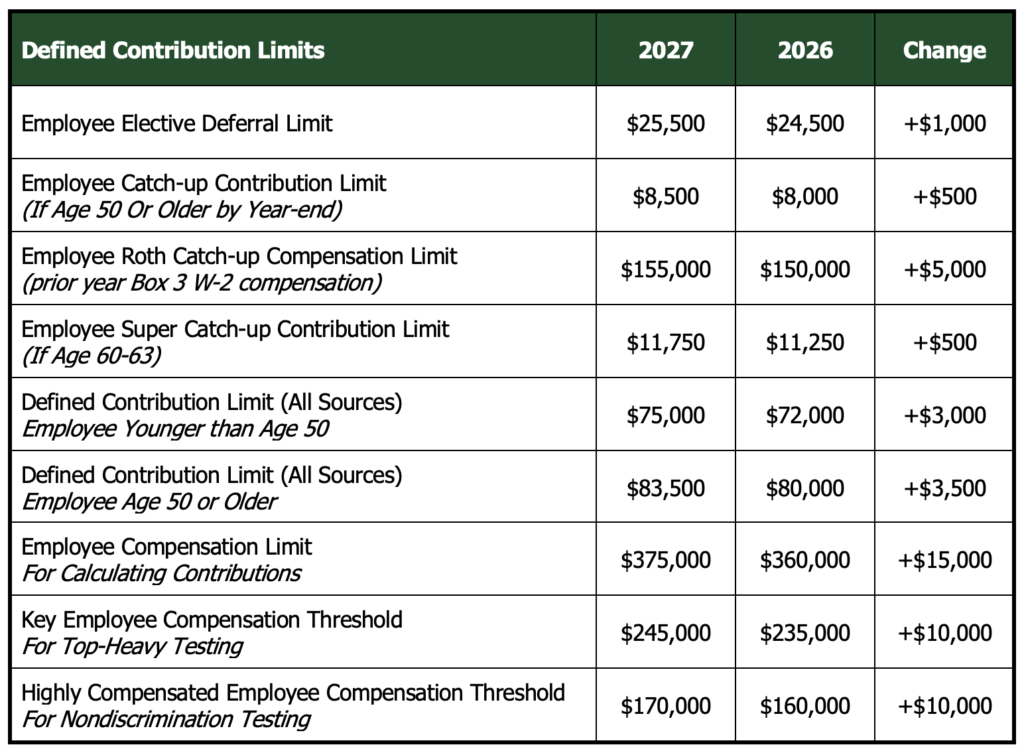
A new rule took effect in 2026. If your FICA wages from your employer were more than $150,000 in 2025, your 2026 catch-up contributions to that employer’s plan must be made as Roth (after-tax) contributions. Your regular employee contribution can still be made pre-tax. If your plan does not offer a Roth option, you may not be able to make catch-up contributions.
Goal – To confirm your catch-up contributions are set up correctly and to plan for the lost pre-tax deduction.
Year-End Tax Payments
If, while doing year-end planning, it is determined that you have underpaid tax throughout the year, you can change your withholding for your last pay period or two.
Goal – Withholding is deemed to be paid evenly throughout the year, so by withholding a larger amount at year-end, you might be able to reduce or eliminate the underpayment penalty.
INCOME AND PORTFOLIO PLANNING
Roth Conversions
If you or your household is in a lower tax bracket for 2026 (due to business loss or other known changes) and you have an IRA(s), you may want to consider converting a portion or all of the IRA to a Roth IRA. Conversions must be completed by December 31 to count for 2026. Individuals should consult their tax advisor regarding their specific situation.
Goal – To pay less tax on the amount converted today vs. what you might have to pay someday in the future when you take it out. Roth accounts grow tax-free.
Senior Deduction
Individuals age 65 or older may be eligible for a new temporary deduction of up to $6,000 per person from 2025 through 2028. It is available whether or not you itemize. The deduction phases out when MAGI is above $75,000 for single filers, or $150,000 for married filing jointly. Married individuals must file a joint return to claim the deduction.
Goal – To preserve the deduction where possible. Roth conversions, capital gains, and other income can reduce it, so review them together before year-end.
Tax Loss Harvesting
If you have securities/stocks in a loss position close to year-end, consider selling them to realize the capital loss.
Goal – To use the capital losses to offset capital gains and if they are not fully used, carry forward indefinitely.
Note – To avoid complicated tax rules (“wash sales”), it may be recommended that you reinvest the proceeds in something similar to the security/stock you sold, but not the same one. Consult a tax professional regarding individual circumstances.
Trust Distributions
Trusts reach their highest tax bracket of 37% at $16,000 of taxable income (rising to $16,500 in 2027). Distributions from a tax-paying Trust shift income from the Trust to the Beneficiary. If you are in a lower tax bracket, you could reduce your overall taxes paid between you and the Trust.
Goal – Pay fewer tax dollars between you and a trust for your benefit. Distributions through March 6, 2027, can be counted for 2026 if elected. Because March 6 falls on a Saturday, plan to complete distributions before that date.
Required Minimum Distributions and Qualified Charitable Distributions
If you are required to take a required minimum distribution (RMD) from a retirement account, make sure it is complete by December 31. If you turned 73 in 2026, your first RMD can be delayed until April 1, 2027, though you would then take two distributions in 2027.
If you are age 70½ or older, you can make a qualified charitable distribution (QCD) directly from your IRA to an eligible charity. The 2026 limit is $111,000 per person. The limit rises to $114,000 in 2027. A QCD counts toward your RMD and is excluded from your income.
Goal – To avoid RMD penalties and, if you give to charity, to satisfy your RMD without increasing your taxable income.
SCHEDULE A – MAXIMIZING ITEMIZED DEDUCTIONS
Bunch Medical Expenses
Taxpayers who itemize may be able to deduct qualifying unreimbursed medical and dental expenses to the extent that eligible expenses paid during the tax year exceed 7.5% of adjusted gross income (AGI). Where appropriate, you should consider the timing of eligible medical payments to maximize potential itemized deductions.
Goal – If itemizing, this would maximize the amount you could deduct on your return.
January’s Mortgage Payment
Only eligible mortgage interest actually paid may qualify; principal payments and escrow deposits are not deductible as mortgage interest.
Goal – If itemizing, this would move more deductible mortgage interest to the current year.
Investment Interest Expense
At year-end, interest paid on debt used to acquire or carry taxable investments may qualify as an itemized deduction, subject to applicable limitations. The deductibility of interest depends on how borrowed funds are used, the type of investment income generated, and other applicable tax rules. Your CPA or financial advisor should be able to help you with that determination.
Goal – To maximize the tax deduction for interest paid.
New Charitable Deduction Rules
Three charitable deduction changes from the One Big Beautiful Bill Act took effect in 2026.
- 0.5% floor for itemizers: Taxpayers who itemize can generally deduct charitable contributions only to the extent that total qualifying contributions exceed 0.5% of AGI. With $500,000 of AGI, for example, the first $2,500 of charitable contributions would not be deductible.
- 35% benefit cap: Certain high-income taxpayers subject to the new limitation on itemized deductions may receive a maximum federal tax benefit of 35% on affected deductions, including eligible charitable contributions. This limitation generally applies to taxpayers whose taxable income exceeds applicable thresholds.
- Deduction for non-itemizers: If you take the standard deduction, you may deduct up to $1,000 ($2,000 for married couples filing jointly) of qualifying cash gifts to eligible public charities. Gifts to donor-advised funds do not qualify.
Goal – To match your giving strategy to how you file. Taxpayers who itemize may want to review whether to give each year or combine gifts into fewer years.
Charitable Giving and Standard Deduction Planning
The 2026 standard deduction is $32,200 for joint filers, $24,150 for heads of household, and $16,100 for single filers. For 2027, the standard deduction rises to $33,200 for joint filers, $24,925 for heads of household, and $16,600 for single filers. If you donate to charities but are not itemizing, or want to reduce the effect of the 0.5% floor, you might want to consider “Charitable Stacking,” which combines several years of planned gifts into one tax year.
Beginning in 2026, taxpayers who take the standard deduction may also deduct up to $1,000 ($2,000 for married couples filing jointly) of qualifying cash charitable contributions to eligible organizations. Contributions to donor-advised funds and noncash gifts do not qualify for this additional deduction.
Goal – Optimize your giving while utilizing the standard deduction in other years.
Cash Charitable Contributions
Cash contributions to qualifying public charities may be deductible up to 60% of AGI. Appreciated noncash assets held longer than one year are generally subject to a 30% limit. Contributions exceeding applicable limits may be carried forward for up to five years.
Goal – Reduce taxable income through charitable giving while maximizing available deductions.
Consider a Donor-Advised Fund (“DAF”)
A DAF is a charitable investment account. From this account, you can direct the funds to go to the majority of public charities. If you donate cash to the donor-advised fund, you get a deduction of up to 60% of adjusted gross income. If you donate appreciated securities to the donor-advised fund, you can deduct up to 30% of adjusted gross income. These deductions are subject to the 0.5% floor and 35% benefit cap described above.
Goal – Help the charity(s) of your choice, lower income taxes in a high-income year, and excess contributions carry forward five years.
Note – Talk to your adviser about possibly giving other appreciated assets like real estate, partnership interests, or private stock.
Non-Cash Property – Need an Appraisal?
If you have made a contribution of non-cash property worth more than $5,000, you will need a qualified appraisal. (This does not apply to stock/securities that are valued on an ongoing basis.)
Goal – Properly document large non-cash gifts so they will be deductible on your tax return.
OTHER ITEMS
Annual Exclusion Gifts and Lifetime Exemption
Annual exclusion gifts of up to $19,000 per recipient in 2026 ($38,000 for married couples who split gifts) do not use any of your lifetime exemption. In 2027, the annual exclusion rises to $20,000 per recipient ($40,000 for couples). The federal lifetime gift, estate, and generation-skipping transfer (GST) exemption is $15,000,000 per person in 2026 and rises to $15,480,000 in 2027.
Goal – To use your 2026 annual exclusion before it resets on January 1, and to review with your adviser whether larger gifts fit your estate plan.
Social Security: 2027 Wage Base and Cost-of-Living Adjustment
The Social Security wage base, which is the maximum earnings subject to the 6.2% Social Security tax, rises from $184,500 in 2026 to $192,300 in 2027. Social Security and SSI benefits will also receive a 3.6% cost-of-living adjustment beginning in January 2027.
Goal – To help you plan 2027 payroll withholding and retirement income.
Fund 529 Plans Before Year-End
If considering a 529 plan contribution in the coming months, make it before year-end. There are a number of states which allow a deduction or credit for contributions. Growth in these funds grow tax-free and may be withdrawn tax-free when used for qualified education expenses.
As always, if you have any questions relating to the above year-end considerations, please contact your TFO Wealth Partners adviser. We would be happy to help.